Capital Markets & Structuring
Structuring the Capital Stack: Mezzanine Debt vs. Preferred Equity in Commercial Real Estate
How two forms of gap capital differ in collateral, cost, enforcement, and control, and how sponsors weigh them when the senior loan does not cover the full purchase.
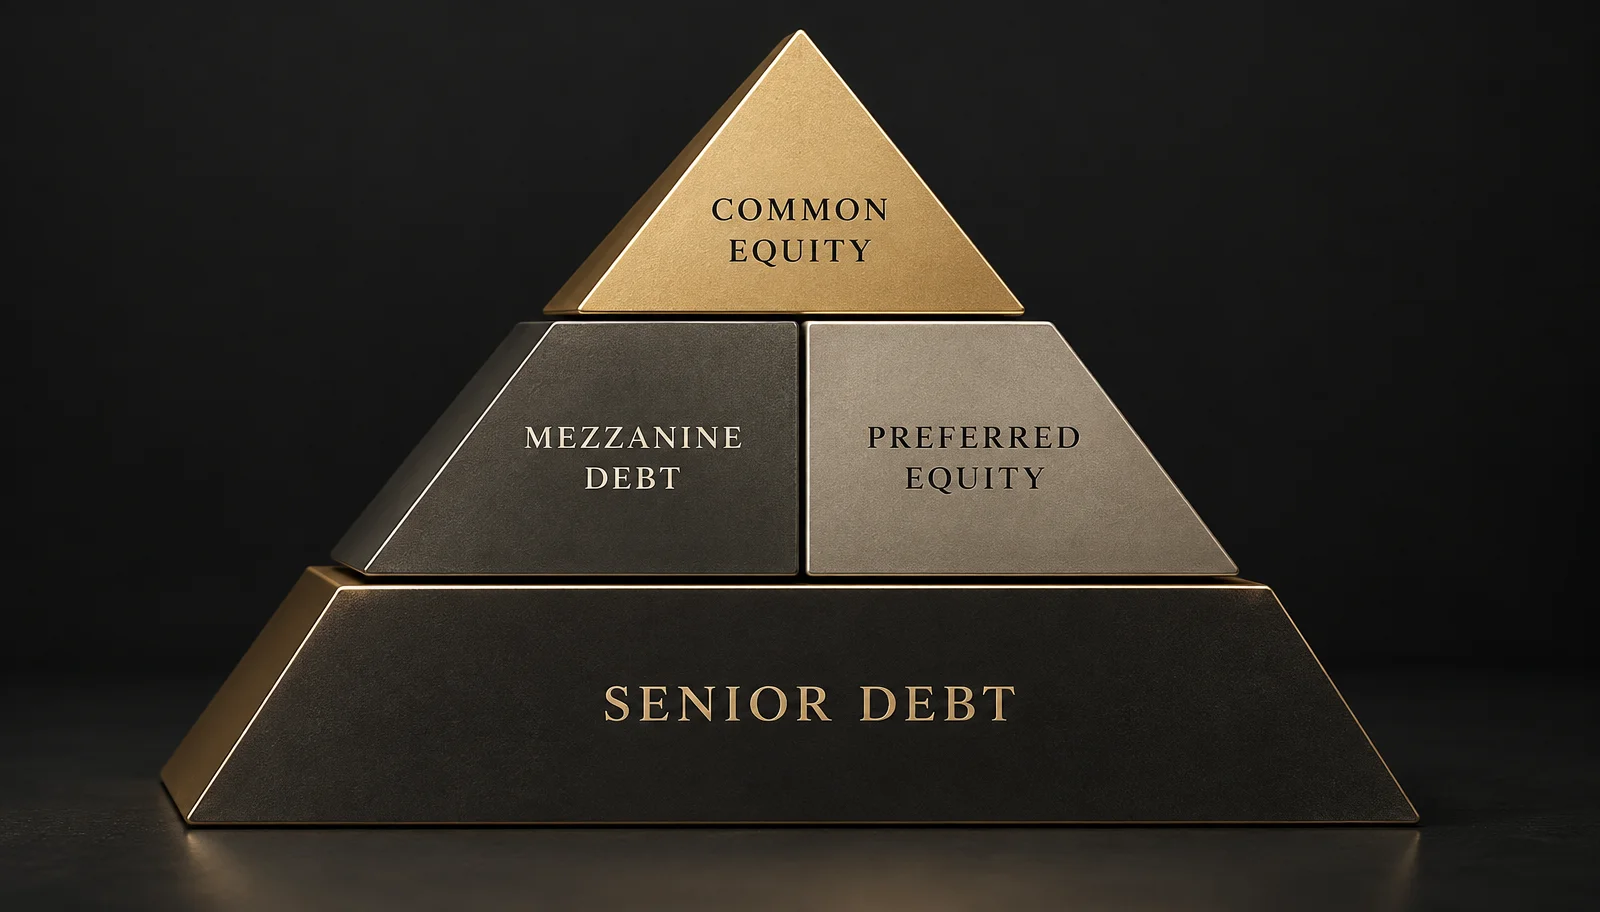
Most commercial real estate acquisitions are financed with more than one layer of capital. At the base of the capital stack sits senior debt, typically a first mortgage from a bank, life company, or CMBS lender. At the top sits common equity, the sponsor's and investors' own money. Between them there is often a gap.
Senior loan leverage varies by lender, property type, market conditions, sponsor, debt yield, DSCR, asset quality, and capital-market conditions. Mezzanine debt and preferred equity are two forms of subordinate or gap capital that can sit between senior debt and common equity. They can look similar on a sources-and-uses table, but they are built on different legal foundations, and those differences matter most when a deal underperforms.
Illustrative capital-stack example only
Consider a hypothetical $50,000,000 acquisition where, as an illustrative leverage example, the senior lender provides 65% Loan to Value:
The 65% figure is not current Price Capital Group, bank, CMBS, or market pricing. A sponsor in this position might fund the full $17,500,000 with common equity, or fill part of it with gap capital.
Illustrative higher-leverage capital-stack scenario
In some transactions, gap capital may bring total leverage to roughly 80% to 85% of the purchase price. Total leverage varies materially by transaction and may be limited by the senior lender, gap provider, sponsor equity, asset risk, and market conditions.
1. The Anatomy of Mezzanine Debt
Mezzanine financing often sits behind the senior mortgage and may be secured by a pledge of equity interests in the property-owning entity rather than a subordinate mortgage on the real estate. In a common structure, the mezzanine lender lends to a parent entity that owns the property-owning borrower, and takes a security interest in that ownership. Structures and enforcement can vary by jurisdiction and transaction.
Foreclosure Mechanism
Certain mezzanine loans are secured by pledged ownership interests and may be enforced through remedies governed by Article 9 of the Uniform Commercial Code. UCC remedies can sometimes proceed more quickly than real-property foreclosure, but timing depends on the loan documents, notice requirements, commercial reasonableness, litigation, jurisdiction, and other circumstances.
Illustrative timeline only
In some cases, a UCC sale of pledged interests has been described as taking roughly 30 to 60 days.
After enforcement against pledged equity interests, a mezzanine lender or purchaser may obtain control rights over the borrower entity, subject to the UCC process, intercreditor agreement, senior-loan restrictions, and governing documents. Any change of control must comply with the senior loan and intercreditor agreement. The senior debt does not automatically remain unaffected.
Cost Profile
Mezzanine debt may include current-pay interest, accrued interest, PIK components, exit fees, or other economics depending on the transaction. Pricing depends on seniority, collateral, current-pay requirements, control rights, sponsor strength, leverage, asset risk, and negotiated economics. Mezzanine debt may or may not be cheaper than preferred equity in a given deal.
2. The Structure of Preferred Equity
Preferred equity generally represents an ownership interest with negotiated priority economics and control rights, rather than a mortgage loan. The provider invests in the ownership entity, usually through the operating agreement, instead of lending to it. Preferred equity structures are not all alike.
The relative risk of mezzanine debt and preferred equity depends on the specific capital stack, enforcement rights, senior-lender restrictions, cash-flow priority, and control provisions. Preferred equity documents typically establish priority economics ahead of common equity, subject to available cash flow and the governing agreements.
Hard Pref vs. Soft Pref
For purposes of this article, "hard pref" describes structures with stronger current-pay or mandatory-payment features, while "soft pref" describes structures where some preferred return may accrue rather than be paid currently. Actual terminology varies.
- Hard pref: Certain preferred equity agreements may grant enhanced control, replacement, or management rights after specified payment defaults or other trigger events. Those rights depend on the operating agreement, the preferred equity documents, any recognition agreement, and senior-lender restrictions.
- Soft pref: Unpaid preferred returns may accrue and be paid later. Accrued preferred returns, compounding, redemption terms, and payment priority depend on the governing agreements.
Some preferred equity structures include participation in sale or refinancing proceeds, increasing the provider's total return if the asset performs well. For a deeper look at waterfalls and downside protection, see How to Structure Preferred Equity in Commercial Real Estate.
3. The Intercreditor and Recognition Agreements
An intercreditor agreement can govern the relationship between the senior lender and mezzanine lender, including cure rights, standstill periods, transfer restrictions, enforcement rights, and qualification standards for a successor owner. Provisions differ from transaction to transaction. Our guide to mezzanine debt, intercreditor agreements, and UCC foreclosures covers these terms in more detail.
A recognition or similar agreement may address how the senior lender recognizes the preferred equity provider's negotiated rights. Not every preferred equity transaction uses a document with that name.
Transfer, control, and cure rights should be coordinated with the senior loan documents to avoid unintended defaults or recourse consequences. Many senior loans contain non-recourse carve-outs tied to unauthorized transfers, explained in Understanding Bad Boy Carve-Outs and Non-Recourse Debt in Commercial Real Estate. Sponsors and guarantors should review these documents with qualified counsel.
4. The Trade-Off: Cost versus Control
The relevant question is not only which capital source has the lower stated rate, but how each component affects the blended cost of the entire capital stack, often described as the Weighted Average Cost of Capital.
Mezzanine debt may be attractive where the sponsor values fixed contractual economics and can support the required current-pay burden. Mezzanine debt generally does not involve the same type of equity participation as preferred equity, although warrants, fees, profit participation, or other economics may be negotiated. A mezzanine default can create significant control risk because enforcement against pledged equity interests may occur more quickly than traditional real estate foreclosure in some circumstances.
A structure with accruing preferred returns may offer more flexibility during periods of uneven property cash flow, such as a value-add business plan, but it can increase the amount owed at a future capital event. The trade-off may be higher total capital cost or greater participation in future upside.
Neither option is right for every deal. The answer depends on cost, cash flow, leverage, duration, asset volatility, control rights, and exit strategy. Our cap rate calculator can help frame the income side of that analysis.
Many capital-structure problems start with decisions made before closing. We discuss that idea in Why Small Businesses Fail Before They Even Start and in The Discipline Loop: Why Your Process Beats Your Goals.
When the Capital Stack Comes Under Pressure
A sponsor facing pressure from subordinate capital should evaluate available refinancing, recapitalization, restructuring, and disposition options before control rights or enforcement remedies become more difficult to manage.
Price Capital Group evaluates commercial real estate acquisition and capital-structure opportunities based on the asset, leverage, ownership structure, capital need, and transaction circumstances. If you own a property with a layered capital stack, we offer a confidential transaction review.
Related Reading
- The Complete Guide to the Commercial Real Estate Capital Stack: Senior Debt, Mezzanine Capital, Preferred Equity, and Common Equity
- Understanding Commercial Real Estate Debt Yield: The Ultimate Institutional Underwriting Metric
- Understanding Cash Management Lockboxes and Debt Service Reserve Accounts in Commercial Real Estate
- How to Structure Cross-Collateralized Commercial Real Estate Debt: Portfolio Optimization and Release Clauses
This article is general educational information and does not constitute legal, tax, lending, or investment advice. Figures are illustrative. Capital-stack terms, enforcement rights, and timelines depend on the governing documents, jurisdiction, and transaction. Consult qualified advisers before any financing, investment, or sale.