Commercial Leasing
The Complete Guide to Commercial Tenant Improvement Allowances: Turnkey Buildouts versus Rent Abatement
How turnkey buildouts, stated TI allowances, and rent abatement allocate construction cost and risk between landlord and tenant, and how those choices affect lease economics and property value.
In commercial real estate, securing a strong corporate tenant is often celebrated as a major win for a landlord. Agreeing on monthly base rent, however, is only part of the negotiation. Much of the financial risk in a commercial lease sits in the physical preparation of the space. Many corporate tenants will not accept a vacant shell as is. They often request customized floor plans, upgraded electrical systems, specialized lighting, and branded reception areas.
To bridge the gap between a raw shell and an operational suite, landlords and tenants negotiate a commercial tenant improvement allowance. Mismanaging this capital expenditure can seriously impair an owner's returns. If a landlord materially underestimates the cost of commercial construction, buildout spending can consume a significant share of the expected profit from the lease before the tenant opens.
This guide compares three common approaches: a turnkey buildout, a stated monetary allowance, and rent abatement. No single structure is universally superior. The appropriate structure depends on the lease, tenant credit, construction scope, landlord liquidity, negotiated economics, and allocation of cost-overrun risk.
1. The Turnkey Buildout: Total Landlord Risk
In a turnkey negotiation, the tenant typically provides an agreed architectural floor plan, and the landlord generally agrees to deliver the premises in an agreed completed condition, ready for occupancy.
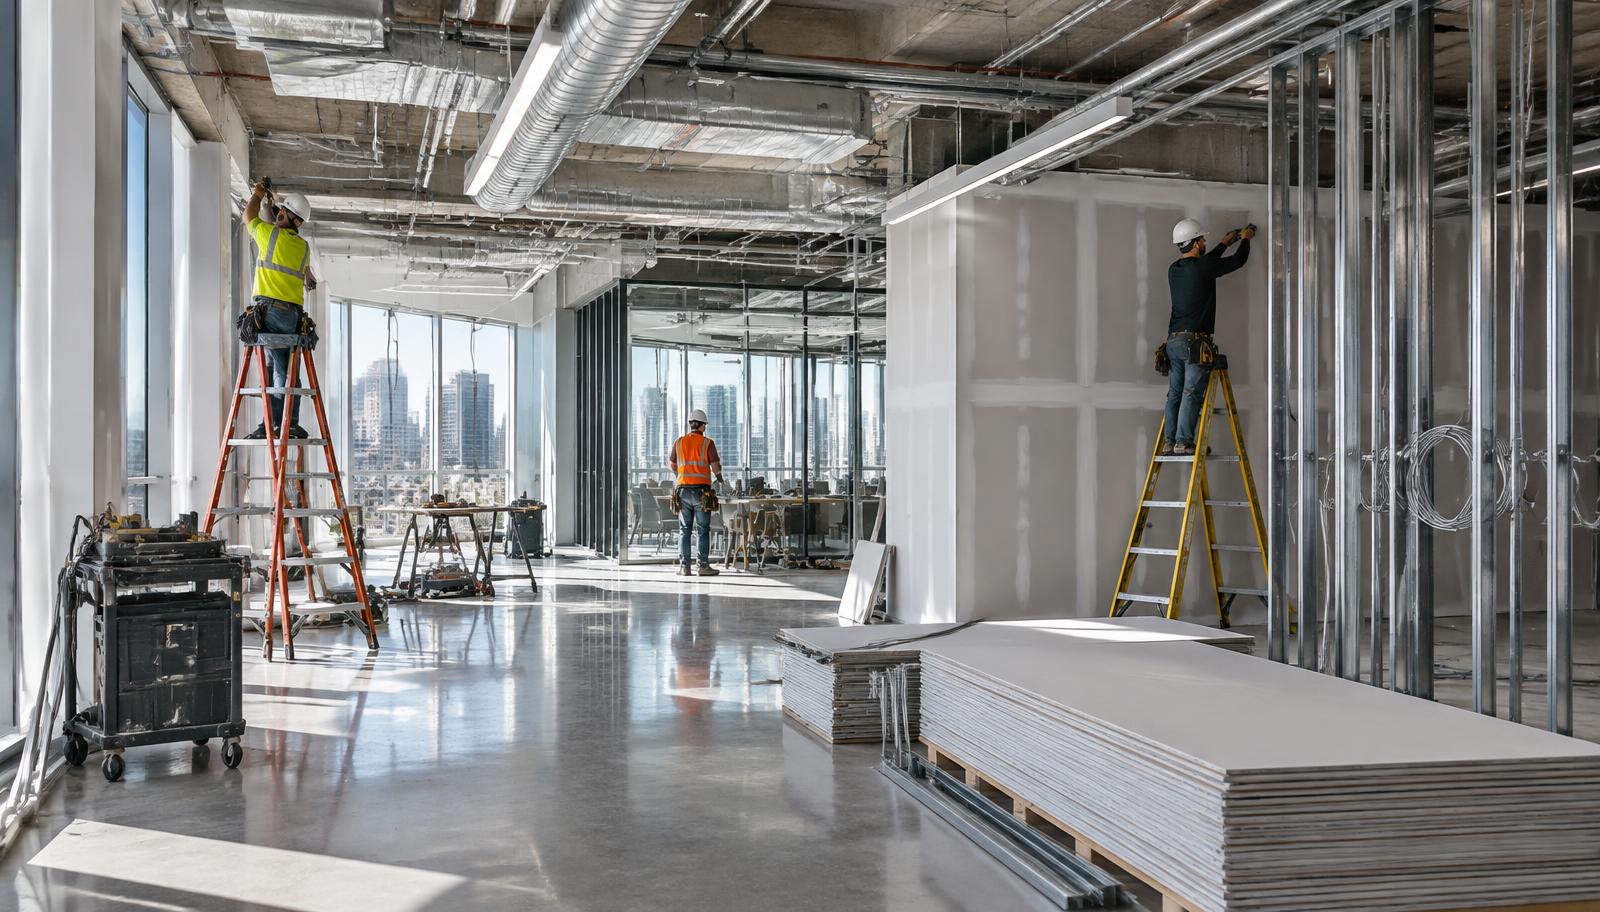
In many turnkey deals, the landlord manages much of the construction process, which can include selecting the general contractor, coordinating municipal permits, overseeing trades such as plumbing and electrical, and paying invoices. The exact division of work varies. In a landlord-delivered turnkey structure, responsibility for construction cost and execution depends on the work letter, plans, allowance language, change-order provisions, exclusions, and negotiated lease terms.
Tenants often favor turnkey buildouts because they can shift much of the construction risk toward the landlord. If material prices rise during the build, or the municipality requires an unbudgeted electrical panel upgrade, the landlord may bear that cost unless the lease and work letter allocate it elsewhere. Tenant-requested change orders, for example, are frequently charged back to the tenant. For independent landlords without substantial liquid reserves, a turnkey commitment on a project that stalls or runs over budget can create serious financial strain. Property operations groups such as BOMA publish standards and resources that can help owners approach tenant buildouts and building management with more discipline.
2. The Stated Tenant Improvement Allowance
To manage exposure to volatile construction costs, many institutional landlords use a stated Tenant Improvement Allowance. Instead of promising a finished product, the landlord commits a specific monetary contribution, commonly calculated per square foot.
5,000 SF × $40/SF = $200,000
Illustrative example: a 5,000-square-foot office with a $40 per square foot allowance.
Under this structure, the tenant often hires its own general contractor and manages construction, although control rights vary and some landlords retain approval over plans, contractors, and building systems. The landlord then typically reimburses approved, eligible construction costs up to the stated allowance, according to the lease's disbursement conditions.
If the total buildout costs $300,000 against a $200,000 allowance, $100,000 exceeds the stated allowance. Where the lease caps the landlord's TI contribution at a stated amount, costs above that contribution are commonly allocated according to the lease and work letter, and in many cases fall to the tenant. This can make landlord capital exposure more predictable. Even so, landlord obligations may still exist for base-building work, code compliance, building systems, approvals, and landlord-required improvements, depending on the agreement.
Comparing the Three Structures
| Structure | Construction Control | Landlord Capital Exposure | Tenant Cost Exposure | Main Negotiation Issue |
|---|---|---|---|---|
| Turnkey | Often landlord-led, subject to lease | Can be less predictable | Depends on scope and change orders | Defined delivery condition |
| Stated TI Allowance | Varies | More clearly capped if documents provide | May bear excess costs | Eligible costs and reimbursement terms |
| Rent Abatement | Often tenant-funded | Reduced upfront cash requirement | Tenant funds buildout | Free-rent period and economics |
3. Rent Abatement: The Invisible Capital Strategy
Consider a landlord who wants to attract a high-quality tenant but lacks $200,000 of immediate liquidity to fund a TI allowance. Commercial rent abatement can offer an alternative way to structure economic support.
With rent abatement, or free rent, the tenant may fund some or all of the buildout with its own capital, and the landlord waives or reduces base rent for a negotiated period. As an illustrative example, the landlord might offer six months of free rent at the start of a ten-year lease. Abatement periods vary widely, and there is no standard term. The tenant may use the rent savings to help pay its general contractor, although abatement does not automatically replace a TI allowance dollar for dollar, and some deals combine abatement with a smaller cash allowance.
Rent abatement can reduce the tenant's occupancy cost during the buildout or opening period, but the economics and lender implications depend on the lease and loan documents. As discussed in Would You Lend 800K on This Burger King Deal, lenders look closely at cash flow. Extended rent abatement can temporarily reduce property cash flow and may affect DSCR or other loan covenants depending on the loan documents. Our guide to debt yield and loan covenants explains how those tests work.
The Mathematical Impact on Property Valuation
When an institutional buyer underwrites a commercial asset, it typically reviews how prior leases structured tenant improvements, concessions, and leasing costs. Significant construction spending can meaningfully affect the true yield of the property.
As shown in What Is a Cap Rate? Running the Numbers on Three Fort Myers Warehouses, Net Operating Income is central to how income property is valued. Effective Net Rent goes a step further by accounting for the capital spent to secure the tenant. The source frames it this way:
Effective Net Rent = Total Rent Collected - Total Tenant Improvement Allowance
Simplified illustrative framework. Effective lease economics should account for rent, concessions, TI expenditures, commissions, and other transaction costs over the relevant lease term.
For example, a lease that generates $500,000 of rent over five years but required a $150,000 turnkey buildout produces materially lower effective economics than the headline rent suggests. Buyers commonly evaluate both property NOI and the recurring capital required to maintain occupancy. Significant near-term leasing costs can affect pricing, required returns, and underwriting assumptions. Our step by step underwriting guide shows how these costs fit into a full analysis.
Bypassing Capital Shortages via Direct Corporate Liquidation
For independent property owners, managing tenant turnover can be exhausting. When a long-term tenant vacates, the suite may be functionally obsolete. Replacing dated finishes and upgrading HVAC ductwork to meet modern tenant expectations can require substantial new capital.
When an owner lacks capital to fund competitive tenant improvements, re-leasing can become more difficult, and prolonged vacancy can reduce NOI and value. A traditional listing may still be the right path for some owners, but a sale process does not by itself solve an underlying shortage of leasing capital.
A direct off-market sale to an established corporate cash buyer is one alternative. Direct buyers may purchase properties with significant vacancy as is, and they typically underwrite vacancy and TI requirements into their acquisition pricing. Responsibility for existing obligations depends on the purchase agreement. Direct capital can reduce financing-related execution risk, may avoid negotiated brokerage commissions, and can support a faster or more defined closing timeline, while still depending on diligence, documentation, and transaction terms.
To evaluate how buying groups analyze property yield and vacancy, test your figures in our cap rate calculator. If you are tired of funding construction buildouts and want a direct corporate cash evaluation, Submit a Property to our acquisition team for a confidential review. For a deeper look at private transaction structures, read our guide on selling commercial property off market.
Submit a PropertyRelated Reading
This article is provided for general informational purposes only and does not constitute legal, construction, accounting, tax, appraisal, lending, or investment advice. Tenant improvement, abatement, and loan obligations depend on the governing documents and the facts of each property. Consult qualified advisers before negotiating or amending a commercial lease.