Commercial Real Estate Finance
How to Underwrite a Commercial Real Estate Deal: A Step by Step Guide
A four step framework for verifying a rent roll, normalizing expenses into a defensible NOI, applying a market capitalization rate, and stress testing debt service coverage before capital is committed.
In commercial real estate, results follow disciplined financial analysis and suffer under emotional decision making. When a newer investor reads a marketing flyer from a listing broker, the projected cash flows are often accepted at face value. Institutional capital allocators work differently. They treat an offering memorandum as a forward-looking sales document that should be dismantled and rebuilt using verified historical data.
Weak underwriting can materially impair returns. If property expenses are underestimated, tenant retention is overstated, or an unrealistically aggressive exit capitalization rate is applied, the capital stack becomes far more sensitive to even a modest market correction.
Below is a step by step guide to how institutional investors approach commercial real estate underwriting models, separate marketing assumptions from verified performance, and calculate a defensible baseline yield. Professional education bodies such as CCIM teach a similar income-based discipline, and the framework here reflects how our own acquisitions team applies it.
Step 1: Strip the Rent Roll to Baseline Reality
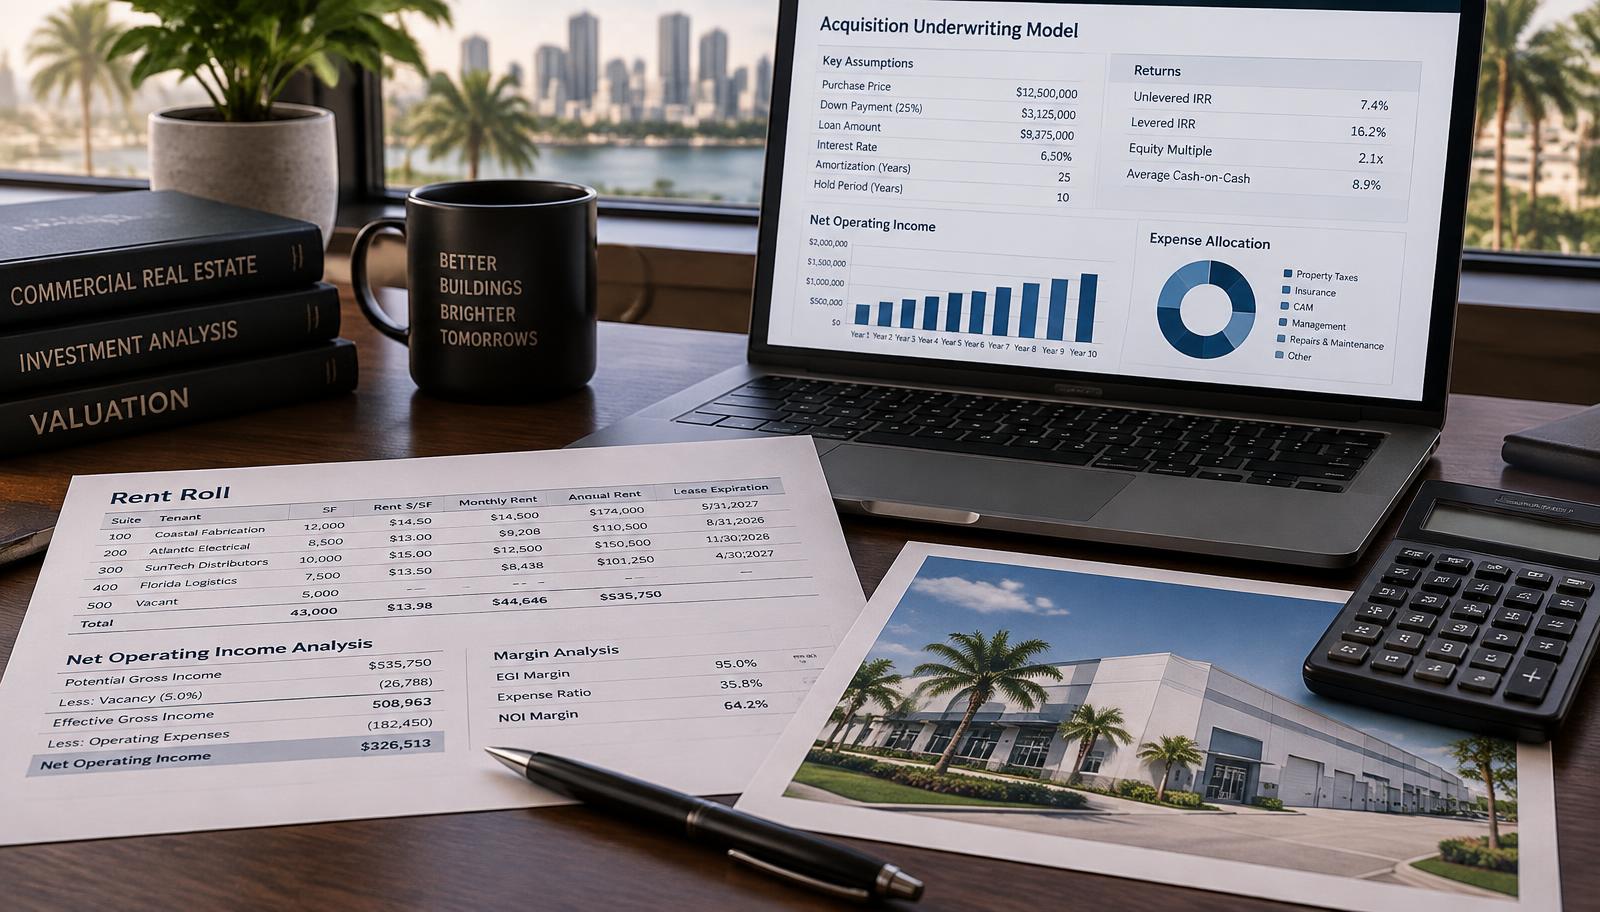
The foundation of every commercial real estate valuation is the active rent roll. Sound underwriting does not accept the top line revenue printed on a broker pro forma. The question is what cash actually reaches the operating account.
Institutional-style underwriting generally seeks to reconcile stated rent with lease documents, collections, operating statements, and other available supporting records. Trailing twelve month financials, bank activity, and tenant estoppels are common sources where a seller can provide them, and the depth of that verification varies with the transaction and the information made available. The practical work looks like this:
- Start with the active rent roll. Build the revenue model from current occupancy and contract rent, not from a stabilized projection.
- Verify actual collections. Compare stated rent to what has been collected over the trailing twelve month period.
- Review lease terms and remaining term. Short remaining term changes the risk profile even when current income looks healthy.
- Identify delinquency and month-to-month tenancy. A tenant sixty days behind, or holding over on an expired lease, is not the same credit as a signed multi-year term.
- Review escalations and landlord responsibilities. Scheduled bumps add income; landlord obligations add cost.
- Reconcile against historical operating information where available. Gaps between the rent roll and the operating statements are usually where the real story sits.
If a broker states that a retail center generates one hundred thousand dollars a month, but two tenants are operating on expired month to month leases and a third is sixty days behind, the verified baseline revenue is meaningfully lower than the pro forma suggests. Offering memoranda often include forward-looking assumptions that should be independently tested against verified historical and market data.
Step 2: Normalizing Expenses and Calculating True NOI
Once real gross income is established, operating expenses are subtracted to calculate net operating income. This is where most underwriting errors appear. The goal is not to assume bad faith on the seller's part, but to assess whether historical expenses are representative of post-acquisition operations. A long-time owner may run the asset in a way a new owner cannot replicate.
Normalizing means adjusting historical costs to reflect the costs the new ownership is realistically likely to incur.
Property Taxes
A legacy owner may be paying a low tax bill tied to an assessment set many years ago. Property tax treatment can change after acquisition depending on jurisdiction, assessment methodology, exemptions, and local law. Underwriters should model taxes using the rules applicable to the subject property rather than carrying the seller's historical figure forward without review.
Property Management
Even an owner who plans to self manage should consider a management line in the model. Management assumptions should reflect the actual operating plan and market. A market-rate management fee is commonly used as a placeholder so the asset can still be valued and financed if ownership later steps away from daily operations, and the percentage applied depends on property type, size, and local management pricing.
Capital Reserves
Roofs, HVAC systems, parking lots, and building systems eventually require capital, even when the seller never budgeted for them. Reserves vary by property type, condition, age, and investment strategy, so the per square foot figure used in one deal will not transfer cleanly to another. Recurring operating expenses such as insurance, utilities, repairs, and CAM should be reviewed on the same basis. In South Florida, insurance in particular has moved enough in recent years that a trailing figure may understate renewal cost.
For a fuller expense and document review sequence, see our commercial real estate due diligence checklist.
Step 3: Applying the Market Capitalization Rate
With verified NOI established, the asset can be valued. As demonstrated in What Is a Cap Rate? Running the Numbers on Three Fort Myers Warehouses, the capitalization rate is the bridge between operational cash flow and property value.
True Asset Valuation = Verified NOI ÷ Market Cap Rate
If rigorous underwriting produces a true NOI of $400,000 and the current market capitalization rate for that asset class is 8%, the indicated value is approximately $5 million.
Indicated Value = $400,000 ÷ 8%
$400,000 ÷ 0.08 = $5,000,000
At an 8% capitalization rate, $400,000 of verified NOI implies an income-capitalization value of approximately $5 million before other adjustments. Cap-rate valuation is one core income approach, not an absolute ceiling. Actual value may also be affected by lease quality, location, physical condition, tenant credit, market liquidity, required capital expenditures, and other valuation considerations. Where a seller's asking price sits well above the indicated value, the gap usually needs to be explained by something verifiable rather than assumed.
Following the principles outlined in The Discipline Loop: Why Your Process Beats Your Goals, the discipline is holding your capitalization rate thresholds and passing on deals that do not clear the required yield. Our cap rate valuation guide covers how those thresholds are set by asset class.
Step 4: Stress Testing the Debt Service Coverage
After establishing asset value, the proposed capital stack has to be stress tested. Leverage can raise total return, and it also increases sensitivity to cash-flow and debt-service changes. The debt service coverage ratio measures property cash flow relative to scheduled debt service.
DSCR = Verified NOI ÷ Annual Debt Service
A DSCR of 1.25x means the property produces $1.25 of net operating income for every dollar of scheduled debt service. Many lenders use minimum DSCR requirements, but thresholds vary by lender, leverage, asset class, loan structure, and market conditions. The more useful exercise is running the ratio under stressed assumptions: higher vacancy, higher insurance, a rate reset at maturity, or the loss of the largest tenant. A model that only clears at the base case is a thinner margin than it appears.
As we analyzed in Would You Lend 800K on This Burger King Deal, cash flow reliability is what carries an asset through market fluctuation and protects the equity position. For the surrounding lender metrics, see our guides on debt yield and loan covenants and DSCR, LTV, and debt yield, along with how leverage flows through the capital stack and into IRR and equity multiple.
Bypassing Friction with Direct Execution
Pursuing an acquisition or a sale on the strength of an untested pro forma is how escrows collapse. As Jason emphasizes in Why Most Businesses Fail Before They Even Start, the absence of rigid operational systems is what puts capital at risk. When a financed buyer discovers significant deferred maintenance during inspections, a scenario we walk through in This Property Looked Like a Deal Until We Got There, physical findings may affect financing or pricing, and in some cases the buyer terminates.
Executing a direct off market transaction with an established corporate cash buyer can reduce financing-related execution risk. Direct acquisition groups underwrite from discretionary capital against verifiable trailing income rather than waiting on a bank credit committee. That structure may also avoid negotiated brokerage commissions and can support a faster or more defined closing timeline, subject to underwriting, documentation, and diligence on the specific asset.
To see how your property performs under institutional metrics, test your target yields in our interactive cap rate calculator. If you are preparing to sell a commercial asset and want a direct corporate cash evaluation based on verified underwriting, Submit a Property to our acquisitions team for a confidential review. For a deeper breakdown of private transaction structures, explore our master guide on selling commercial property off market.
Submit a PropertyRelated Reading
- The Commercial Real Estate Due Diligence Guide and Checklist
- IRR, Equity Multiple, and Cash on Cash Explained
- The Capital Stack in Commercial Real Estate
- Debt Yield, Loan Covenants, and Cash Sweeps
- Cap Rates and Commercial Real Estate Valuation
- How to Transition from Residential to Commercial Real Estate Investing
This article is provided for general informational purposes only and does not constitute legal, tax, financial, investment, appraisal, brokerage, or lending advice. Valuation methods, tax assessment rules, lender requirements, and reserve assumptions vary by jurisdiction, asset class, and transaction. Every acquisition and every credit decision is subject to underwriting, due diligence, documentation, and final approval on the specific property, borrower, and market conditions.